Condo Versus Tenant Insurance: Which Fits?
A burst washing-machine hose can damage more than the floor of one unit. In a Toronto high-rise, water may travel through ceilings, hallways, and several neighbouring suites before the source is found. That is why the choice between condo versus tenant insurance is not simply about who owns the space. It is about what you are responsible for inside it, the belongings you could lose, and the liability costs that could follow an accident.
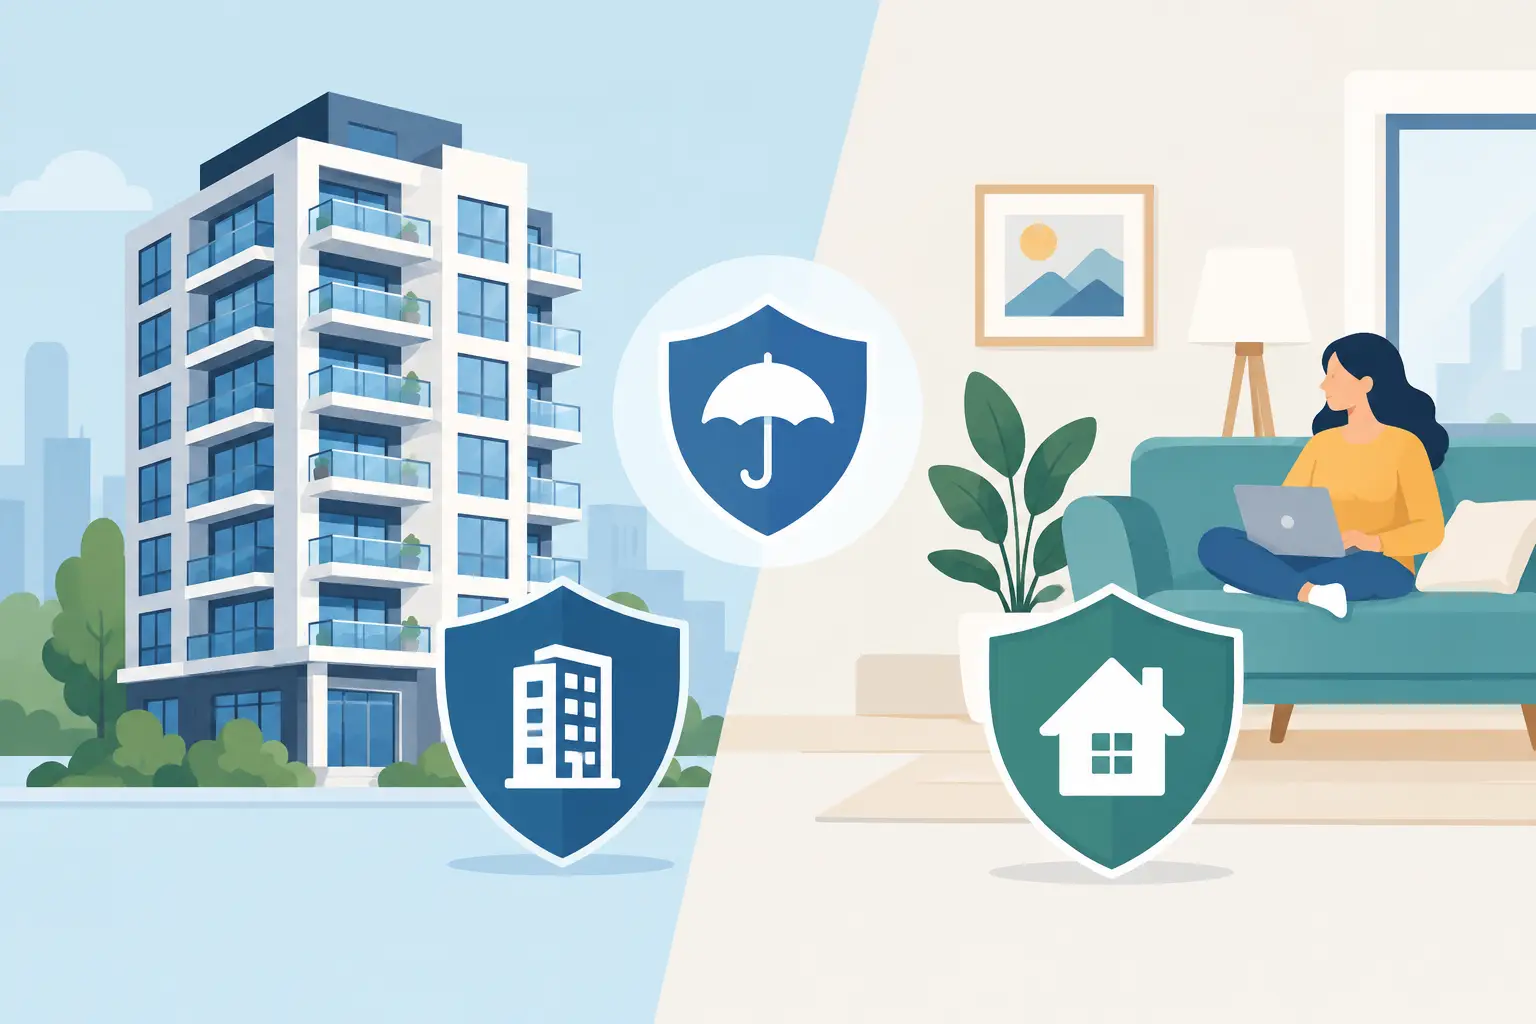
For most people, the answer is straightforward: condo owners need condo insurance, while renters need tenant insurance. The details matter, however, especially in a market where condo corporation deductibles can be substantial and leases may set clear insurance expectations.
Condo Versus Tenant Insurance: The Core Difference
Condo insurance is designed for someone who owns a condominium unit. It generally protects the unit owner’s personal property, personal liability, additional living expenses after an insured loss, and certain improvements or betterments within the unit. Depending on the policy and the condominium corporation’s governing documents, it may also respond to some special assessments or deductible charges for which the owner becomes responsible.
Tenant insurance is designed for someone who rents their home, whether that is a condo unit, apartment, basement suite, or house. It does not insure the building itself because the tenant does not own it. Instead, it typically protects the tenant’s belongings, personal liability, and additional living expenses if the rental home cannot be occupied after a covered loss.
Both policies can be affordable compared with the financial impact of a fire, theft, water loss, or liability claim. The major distinction is the ownership interest. A condo owner has responsibilities connected to the unit and the condominium corporation. A tenant’s insurance is centred on the renter’s possessions and legal responsibility to others.
What Condo Insurance Usually Protects
A condominium corporation carries insurance for the common elements and, in many cases, the building structure. This can include the lobby, elevators, roof, exterior walls, hallways, and shared amenities. That coverage is essential, but it is not a replacement for an individual condo owner’s policy.
Your condo policy can help protect your furniture, electronics, clothing, kitchen items, bicycles, jewellery, and other personal belongings, subject to the policy limits and terms. It can also cover upgrades inside the unit, such as custom cabinetry, flooring, built-in shelving, or higher-end fixtures, when the corporation’s coverage does not fully address them.
One of the most important features is personal liability coverage. If an incident originating in your unit causes injury or property damage to someone else, liability coverage may help with legal defence and settlement costs where you are legally responsible. For example, a leak from your dishwasher supply line could damage another owner’s ceiling and contents.
Additional living expense coverage is another practical safeguard. If an insured event makes your unit temporarily unlivable, the policy may help with reasonable extra costs for accommodations, meals, and related expenses while repairs are completed. This is particularly valuable in the GTA, where short-term accommodations can be expensive.
Condominium deductibles and special assessments
Condo ownership comes with a risk renters usually do not face in the same way: a corporation deductible or special assessment. Condominium corporations may have high deductibles for water damage and other losses. If the corporation determines that an owner is responsible for a loss, or if its declaration permits a deductible chargeback, the owner could face a sizeable bill.
A properly selected condo policy may include coverage for deductible assessments and special assessments arising from insured damage, but coverage rules, limits, exclusions, and the condo corporation’s documents all matter. Do not assume every policy treats this exposure the same way. This is one area where reviewing your unit, building, upgrades, and corporation requirements with a licensed broker can make a meaningful difference.
What Tenant Insurance Usually Protects
Tenant insurance is often misunderstood because renters may think the landlord’s policy will cover their belongings. It normally will not. A landlord insures their own building and property interests, not a tenant’s couch, laptop, clothing, television, or liability.
A tenant policy typically includes contents coverage for your personal possessions if they are damaged, destroyed, or stolen by an insured event. The right amount should reflect the cost to replace what you own today, not what you originally paid for it. A quick room-by-room inventory often reveals more value than expected, particularly when you include electronics, furnishings, cookware, sporting equipment, and seasonal clothing.
It also includes personal liability coverage. If you accidentally start a kitchen fire, leave a tap running, or cause accidental injury to a visitor, you could be held financially responsible. Liability insurance can help protect your savings and future income from the cost of a covered claim.
Like condo insurance, tenant insurance can also provide additional living expenses. If a fire or covered water loss forces you out of your rental unit, your policy may help pay the necessary extra cost of living elsewhere while the unit is repaired.
Your landlord’s policy is not your policy
A landlord may require proof of tenant insurance before handing over the keys. Even where it is not required, the coverage is a practical part of renting responsibly. It protects the tenant, but it also helps reduce disputes after a loss because each party has coverage aligned with their own property and responsibilities.
Read your lease carefully. It may specify a minimum liability limit, often $1 million or $2 million, and may ask you to provide proof before occupancy. If your household includes a roommate, partner, or family member, make sure everyone who should be named on the policy is included. Assumptions about who is covered can become costly after a claim.
Choosing the Right Coverage Amount
The lowest premium is not always the lowest-cost decision. A policy with insufficient contents coverage, a high deductible you cannot comfortably pay, or limited protection for a key risk can leave a serious gap when you need help most.
For condo owners, start with the condominium corporation’s insurance certificate, declaration, bylaws, and information about deductibles. Consider the value of your personal property and unit improvements, as well as the potential financial exposure from a deductible chargeback. If you work from home, own high-value items, or rent out the unit, raise those details during your quote discussion. A standard personal policy may not address every business-use or rental situation.
For tenants, estimate the replacement value of your belongings and choose a liability limit suited to your circumstances. Higher-value jewellery, art, musical instruments, camera equipment, and bicycles may need additional coverage or specific limits. If you have a car, bundling auto and tenant insurance may also be worth exploring, provided the coverage remains suitable.
In either case, ask whether the policy provides replacement cost coverage or actual cash value. Replacement cost generally reflects the cost to replace an item with a comparable new one, while actual cash value considers depreciation. The difference can be significant after a major loss.
Common Situations That Change the Answer
The condo versus tenant insurance question can become less clear when living arrangements change. If you own a condo and rent it to someone else, you need landlord or rented-condo coverage, while your tenant should maintain their own tenant insurance. Your personal condo policy may not be appropriate once the unit is occupied by tenants.
If you live in a condo owned by a parent, spouse, or partner, the ownership and occupancy details should be disclosed to the insurer. If you are moving, tell your broker before the move date. Coverage during a move and the status of both homes can depend on policy wording and timing.
Short-term rentals, extended vacancies, renovations, and home-based business activity also require careful attention. These are not minor administrative details. They can affect whether coverage applies and what insurer is prepared to offer.
Get Advice That Reflects Your Home and Responsibilities
Insurance should follow the reality of your life, not a generic checklist. The age and construction of the building, your condominium corporation’s deductible structure, your belongings, your lease, and whether you are an owner, renter, or landlord all influence the right solution.
A licensed broker can compare available options, explain the differences in plain language, and help you balance suitable limits with a competitive premium. Before the next renewal or move, take ten minutes to review what you own, what your building requires, and who could be affected if a loss starts in your home. That small conversation can protect far more than your furniture.